Solar Business Insurance · Independent agency

Insurance for Solar Energy Contractors

Rooftop and ground-mount, residential and commercial, from the electrical tie-in to panel cleaning and maintenance and solar farm builds: we insure the solar contractors and installers who do the work, and we place each account with the specialty markets on our panel.

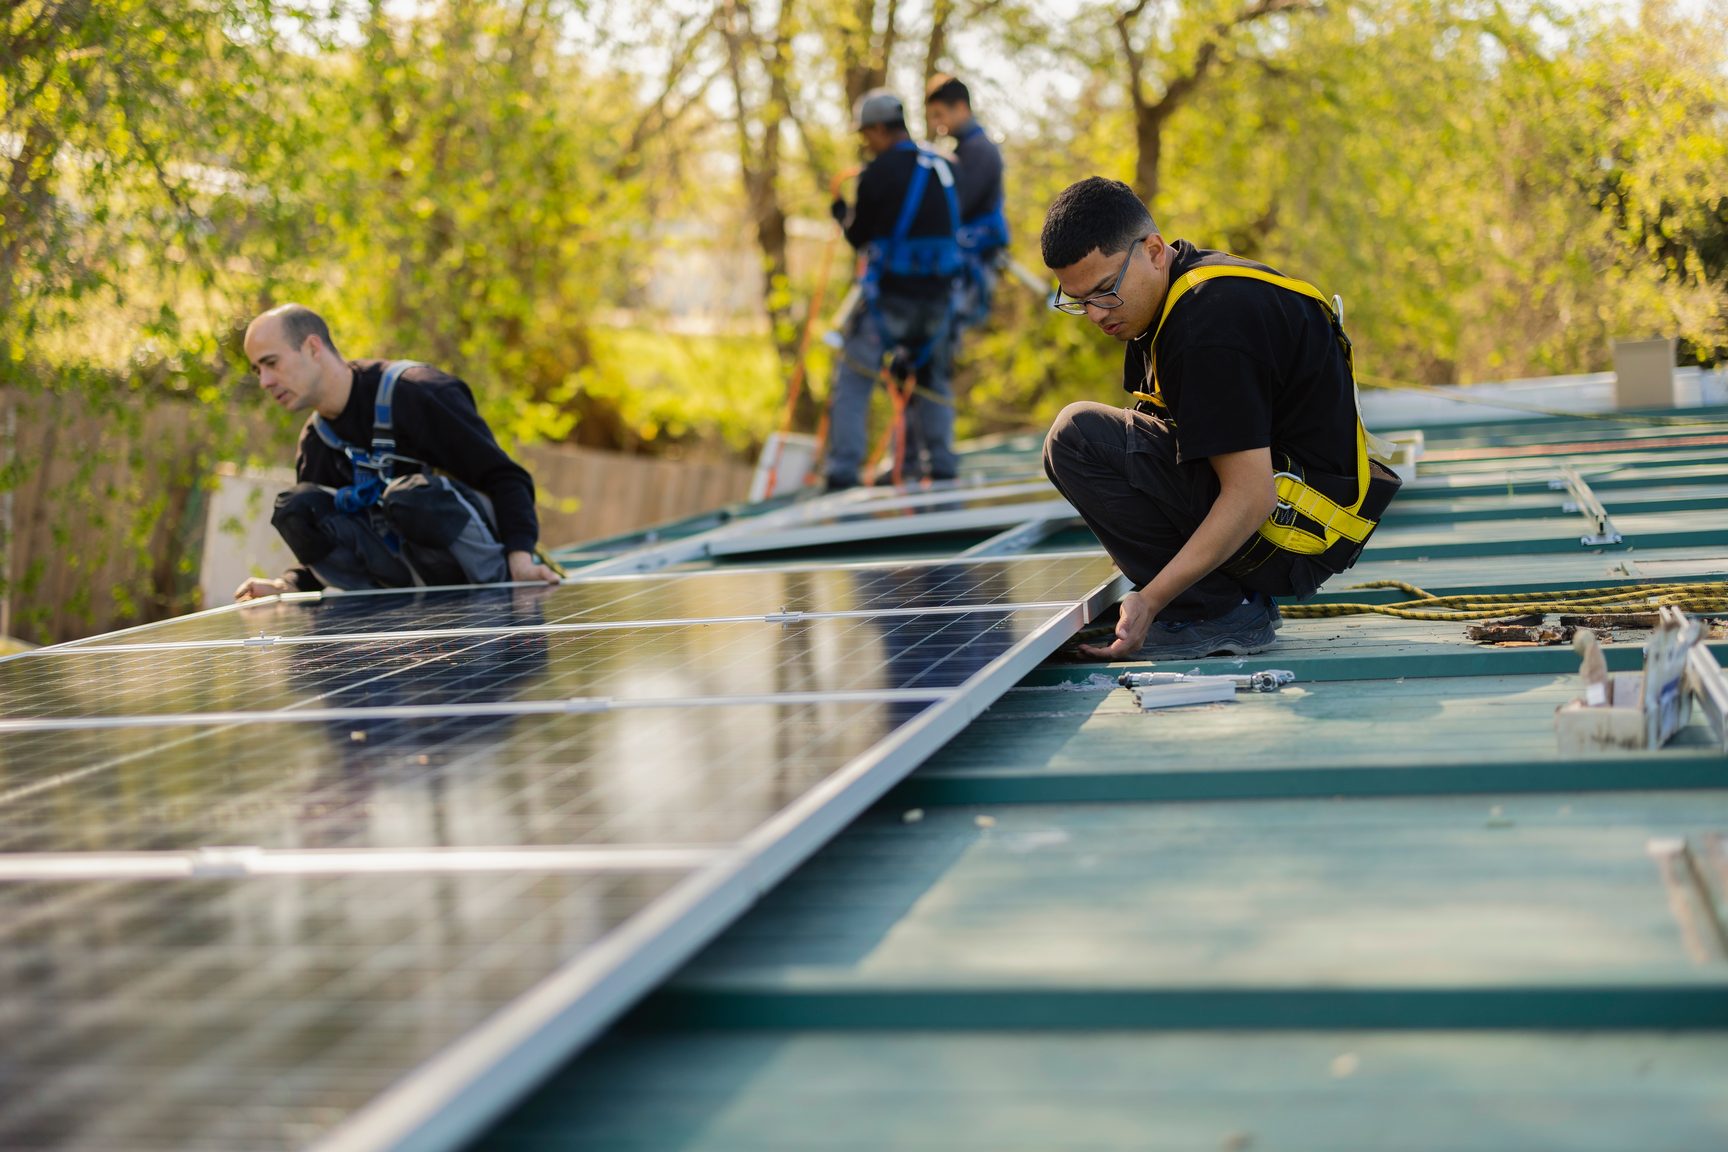
Installers in fall-protection harnesses kneel on a low-slope metal roof, setting solar panels into place on their racking.
50+ Solar Businesses Insured
48 States Licensed
29 Specialty Markets
6 Core Coverages

The solar work we insure

Installing on roofs, cleaning and maintaining arrays that are already running, and building solar farms ask different questions of an underwriter, even inside one solar company. The solar contractor insurance program ties them together.

Roofs, penetrations and the tie-in

Solar Panel Installer Insurance

Residential and commercial rooftop installation puts a crew on somebody else’s roof, drilling through it, and then connects the array to the building’s electrical system. The claims that follow are the leak that shows up after the next storm, a fire traced to the tie-in, and a fall from the roof edge.

Roof access, water and the customer’s system

Solar Panel Cleaning and Maintenance Insurance

Panel cleaning and maintenance means repeat visits to roofs and arrays that are already producing, with water, brushes and sometimes cleaning chemicals. The exposure is the visit itself: a slip on the roof, water where it should not be, and a scratched or cracked panel on a system the customer already owns.

Ground-mount sites, heavy equipment and the contract

Solar Farm Construction Insurance

Solar farm builds are ground-mount construction on large sites, with pile drivers, trenchers and other heavy equipment, under contracts that set the insurance requirements before the work begins. The questions are about the equipment on site, the crews moving across it and the limits the contract asks for.

What a solar company’s insurance is built from

The core coverages, in the order they usually come up for a solar energy contractor.

General Liability

Bodily injury and property damage to others caused by your work, on the job and after the installation is finished.

This is the policy that answers when the installation hurts something: the roof penetration that leaks, the tie-in that starts a fire.

Workers’ Compensation

Benefits for your own employees hurt on the job, and the employer’s liability that sits beside them.

Commercial Auto

The trucks, vans and trailers that carry crews, panels, racking and tools between the yard, the supplier and the site.

Tools and Equipment

Tools, test equipment and gear that travel to the job, with the shop or warehouse and what is stored there as its own section.

Umbrella

Excess liability limits that sit above the general liability, auto and employer’s liability policies.

Professional Liability

The design, system sizing and production-estimate side of the work, where the loss is money rather than damage.

This is the policy that answers when nothing is damaged but the array underperforms because the design, the sizing or the production estimate was wrong.

Questions solar company owners ask

Do you insure solar installers who work alone, or only companies with crews?

Both. An installer who works alone and a company running several rooftop and ground-mount crews are underwritten differently, but they need the same core pieces: liability for the work, coverage for the vehicles and tools and, once there are employees, workers’ compensation.

A roof we installed on started leaking after the job. Which policy answers that?

Physical damage caused by an installation is a general liability question, and a leak at a roof penetration is the classic example. How a particular claim is handled turns on the policy wording and on what failed, which is why we read the completed-work terms with you before a loss, not after.

A customer says the system produces less than we estimated. Is that general liability?

Usually not, because nothing was damaged. A loss that comes from a design, system sizing or production-estimate error is the territory of professional liability. These policies answer different questions, and a solar company that designs and sizes its own systems needs to know which one it carries.

We subcontract roof work or the electrical tie-in. Does our insurance cover the subcontractors?

It depends on whether they carry their own liability and workers’ compensation coverage. Collecting their certificates before the job starts, and checking them against what your contract requires, is the habit that keeps their work from becoming your claim.

Do you insure panel cleaning and maintenance businesses and solar farm builders too?

Yes. Panel cleaning and maintenance companies and the contractors who build ground-mount solar farms are part of the same trade, with different exposures: repeat roof access and the customer’s existing system on one side, heavy equipment, large sites and contract requirements on the other.

A general contractor wants a certificate before we start. Can you help?

Yes. We issue certificates of insurance and can add a general contractor as an additional insured where the policy allows it. Send us what the contract asks for and we will check it against your policy before you sign.

Do you publish typical rates?

Premium depends on payroll, subcontracted work, vehicles, tool and equipment values, the work you take and the states you take it in. We do not publish typical rates because there is no such thing as a typical solar contractor.

How do you decide which insurance company sees my account?

By where the appetite is for your state, your payroll, your mix of residential and commercial work, rooftop and ground-mount, and your loss history. Appetite is not the same everywhere and it changes, which is why we place the account rather than sell one company’s policy.

Who we are, and how we place this work

Solar Business Insurance is a brand of Wexford Insurance, LLC, an independent agency licensed in 48 states. Independent means no single insurance company owns the answer — we place the account where the appetite is.

Our panel is 29 carrier markets we hold appointments with: West Bend Insurance Company, Goodville Mutual, SECURA, Grand River Insurance, Liberty Mutual, Travelers Insurance, The Hartford, Brickyard Insurance Company, AMERISAFE, Texas Mutual, SFM Mutual, Hastings Insurance, Cincinnati Insurance, CNA, AmTrust, Encova, Donegal Insurance Group, Frank Winston Crum, ICW Group, Markel, NEXT Insurance, Ohio Mutual, Pie Insurance, Progressive Commercial, GEICO, THREE by Berkshire Hathaway, Westfield Insurance, Crum & Forster and Tokio Marine HCC.

Wexford Insurance, LLC is a licensed independent insurance agency, NPN 19887690. You can verify our licensing at NIPR.com.

Get a quote for your solar company

A licensed agent reads every submission and comes back with what the markets will do.